
Most of us get paid once a month, but very few of us decide in advance where each dollar of that pay should go.
Without a plan, spending tends to fill whatever is in the account. Saving becomes whatever happens to be left at the end of the month, which is often not much.
The 50/30/20 rule is one of the simplest ways to change that. It does need some adjusting for Singapore, mainly because of CPF, so I’ll cover that too, along with how to set the rule up in seven steps.
Key Takeaways
Figures are for employees aged 55 and below, based on MOM and CPF Board data, with calculations by SmartWealth.
- The 50/30/20 rule divides your take-home pay into 50% for needs, 30% for wants, and 20% for savings, with any debt repayment above the minimum counted as savings.
- In Singapore, the rule works best on take-home pay after employee CPF. Employees aged 55 and below contribute 20% of their wages, and employers add another 17%, on Ordinary Wages of up to $8,000 a month in 2026.
- An employee earning the June 2025 median gross monthly income of $5,775 (including employer CPF) would take home about $3,949 a month, which puts about $790 into the 20% savings bucket.
SIDE NOTE
A policy bought years ago. Savings in three places. A will that's still on the to-do list.
None of it is wrong. It's just not a plan yet.
There's an order that turns the pieces into one system, and it doesn't require becoming a finance expert. Here's the order, in 7 steps, so you know what to sort out first.
What Is the 50/30/20 Rule?
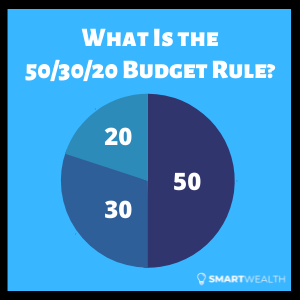
The 50/30/20 rule is a budgeting guideline that splits your after-tax income three ways: 50% for needs, 30% for wants, and 20% for savings.
It was popularised in All Your Worth: The Ultimate Lifetime Money Plan, a 2005 book by Elizabeth Warren (now a US senator) and her daughter, Amelia Warren Tyagi.
Its appeal is simplicity. For every dollar you spend, you only need to ask one question: is this a need, a want, or money for my future self?
50% for needs
Needs are the costs you can’t avoid, such as housing, healthcare, and getting to work.
In Singapore, these usually include:
- Your housing loan instalment or rent
- Service and conservancy charges, and utilities
- Groceries and everyday meals
- Public transport, or the essential running costs of a car you need for work
- A mobile phone plan
- Premiums for protection insurance, such as term life cover and the cash portion of your Integrated Shield Plan
- Minimum repayments on any loans
- Childcare, school fees, and allowances for parents who depend on you
If you have children or support your parents, your needs will naturally be higher, and the split may need adjusting.
30% for wants
Wants are the things you enjoy but could live without, such as holidays, restaurant meals, shopping, hobbies, and streaming subscriptions.
The harder ones to spot hide inside your needs. Getting to work is a need, but taking a Grab every day instead of the MRT is partly a want. A phone plan is a need, but paying off the newest flagship phone in instalments is mostly a want.
A simple way to sort these: count the most affordable reasonable option as a need, and treat the extra cost of the upgrade as a want.
In my opinion, this is where most budgets go wrong without anyone noticing. You don’t have to give up every upgrade, but you should know which ones you’re paying for.
20% for savings and investments
The last 20% is for your future: building an emergency fund, investing, and paying off debt faster than the minimum.
An emergency fund comes first. MoneySense, the national financial education programme, suggests keeping three to six times your monthly expenses as emergency savings.
In my opinion, aim for the higher end (or beyond it) if you have dependants, a mortgage, or an income that changes from month to month.
Once your emergency fund is in place, the 20% can go towards longer-term goals. That could mean topping up your retirement savings or exploring investment options for retirement that match how much risk you can take.
Savings-type insurance plans, such as endowments, belong in this bucket rather than under needs, because their main job is to grow your money rather than protect your income.
Should You Use Your Gross Salary or Take-Home Pay?
Use your take-home pay, which is the amount that lands in your bank account after your employee CPF contribution is deducted.
That’s the money you can actually spend or move. It’s close to the after-tax income the rule was designed for, with one difference: Singapore doesn’t deduct income tax from your monthly pay, so you’ll need to budget for it separately (see step 3).
For Singapore Citizens and Permanent Residents from their third year of PR status, CPF Board’s 2026 contribution table sets the rates for employees aged 55 and below at 20% from the employee and 17% from the employer, or 37% of wages in total.
These rates apply to Ordinary Wages up to a ceiling, which reached $8,000 a month on 1 January 2026. So your own monthly CPF deduction on ordinary wages tops out at $1,600, however much you earn.
What does this mean for your budget?
It means a large share of your pay is already being saved before you’ve budgeted a single dollar. That’s why I’d keep CPF separate from the 20%.
There are two reasons for this. First, CPF savings are set aside mainly for housing, healthcare, and retirement, so they can’t act as an emergency fund. Second, for many homeowners, a large part of the Ordinary Account goes straight to the housing loan each month.
You can see how your contributions are split across your accounts in our guide to CPF contribution and allocation rates.
Two groups should note the differences:
- PRs in their first two years contribute at lower, graduated rates, so their take-home pay is a larger share of their salary.
- Foreigners on work passes don’t contribute to CPF at all. Their 20% savings bucket is their main retirement savings, so in my opinion it’s worth aiming higher than 20%.
What the 50/30/20 Rule Looks Like at Different Salaries
On a $6,000 monthly salary, an employee aged 55 or below would take home $4,800 after CPF. The 50/30/20 rule then gives $2,400 for needs, $1,440 for wants, and $960 for savings.
Here’s how the numbers work out across different pay levels:
| Monthly salary | Take-home pay | Needs (50%) | Wants (30%) | Savings (20%) | CPF (you + employer) |
|---|---|---|---|---|---|
| $3,000 | $2,400 | $1,200 | $720 | $480 | $1,110 |
| $4,936 (median earner) | $3,949 | $1,974 | $1,185 | $790 | $1,826 |
| $6,000 | $4,800 | $2,400 | $1,440 | $960 | $2,220 |
| $8,000 | $6,400 | $3,200 | $1,920 | $1,280 | $2,960 |
| $10,000 | $8,400 | $4,200 | $2,520 | $1,680 | $2,960 |
Monthly salary here means your wage before employee CPF. Figures are SmartWealth calculations for Singapore Citizens and PRs (third year onwards) aged 55 and below, rounded to the nearest dollar.
The median row is based on MOM data. The median gross monthly income of full-time employed residents was $5,775 in June 2025, a figure that includes employer CPF and one-twelfth of annual bonuses.
Taking out the employer’s 17% leaves a monthly wage of about $4,936. You can see how this compares across ages and jobs in our look at salaries in Singapore.
Two things stand out from the table.
First, CPF adds a lot on top of your cash savings. On a $6,000 salary, $2,220 goes into CPF each month, more than twice the $960 in the 20% bucket.
Second, CPF stops rising above the $8,000 ceiling. Below it, each $1,000 pay rise adds $800 to take-home pay. Above it, the full amount reaches your bank account, which is why take-home pay rises by the whole $2,000 between the last two rows.
Does the 50/30/20 Rule Work in Singapore?
Yes, as a starting point for most salaried workers. Whether your needs fit within 50% usually comes down to one thing: housing.
If you own an HDB flat and pay the loan mostly from your CPF Ordinary Account, much of your biggest need never touches your take-home pay. Your cash needs may come in well under 50%. If that’s you, consider moving the surplus into savings so it doesn’t end up being spent on wants.
If you pay a large mortgage mostly in cash, or rent privately, housing alone can take up a large part of the 50%.
How to Budget Your Salary With the 50/30/20 Rule in 7 Steps
To budget with the 50/30/20 rule, work out your take-home pay, check what you spent last month, sort it into needs, wants, and savings, set your split, automate it with separate accounts, trim what doesn’t fit, and review it every month.
1) Work out your real take-home pay
Start with the salary that reaches your bank account after employee CPF.
Add other income you can rely on every month, such as rental income or regular dividends.
Leave out your bonus and any commission you can’t count on. MoneySense’s budgeting checklist gives the same advice: budget on money you’re sure of, not money you hope to get.
QUICK CHECK
Can you answer these three questions?
1) If something happened to you tomorrow, how much would your family receive?
2) At 65, what monthly income will your savings and investments pay you?
3) If you never get round to a will, who inherits what, and in what proportion?
Most people manage one at best. Not because they're careless, but because nobody has shown them which order to tackle things in.
That order exists. Work through your finances in this sequence, from income and protection through to investments and estate planning.
2) Look at what you spent last month
Before setting any targets, find out where your money actually goes. It’s a step many people skip: in a SmartWealth survey on spending habits from 2021, 52% of adults said they didn’t know how much they spend each month.
Your bank and credit card statements are the easiest place to start.
In my experience, logging every coffee in an app is hard to keep up. What works better for many people is putting most spending on one card and avoiding cash where possible, so that a single statement shows nearly everything.
For a quick total, try our budget and expense calculator. If you’d rather keep your own records, FinSnap, our free budgeting template, lets you track your own categories over time.
3) Sort each expense into needs, wants, or savings
Go through each item and put it into one of the three buckets.
Don’t forget costs that come once or twice a year, such as insurance premiums paid annually, your income tax bill, road tax, and festive spending. Divide each by 12 and add it to the right bucket, so the bill doesn’t come as a surprise.
Income tax is easy to forget. Singapore doesn’t deduct it from your monthly salary, so your take-home pay is still before tax. IRAS lets you pay by GIRO in up to 12 monthly instalments. To lower next year’s bill, see the reliefs in our guide to reducing your income tax.
4) Set your split
Compare your numbers with 50/30/20. If your needs are under 50%, you may be able to save more than 20%. If they’re over 50%, take the difference from wants first and protect your savings where you can.
Fix your savings amount first, since that’s what you’ll move out on payday.
5) Split your salary across separate accounts
With everything in one account, it’s hard to tell how much you can really spend. A simple set-up uses three:
- Salary account: pay comes in and bills for needs go out.
- Savings account: your 20%, including your emergency fund.
- Spending account: your 30% for wants, to spend freely until it runs out.
Set up a standing instruction so the money moves automatically a day or two after payday. That way, you don’t have to remember to save each month.
6) Keep, swap, or cut each expense
For every item on your list, make one of three choices:
- Keep it as it is
- Swap it for a more affordable option that does the same job
- Cut it completely
Start with wants and subscriptions, but look at needs too. A cheaper phone plan, for example, can free up money without changing your lifestyle much.
7) Review monthly and track your net worth
Check your statements against your buckets once a month. Every six months or so, use a net worth calculator to see whether your assets are growing and your debts shrinking.
50/30/20 vs Other Budgeting Rules
The 50/30/20 split is only one option. Other rules of thumb divide your pay in different ways, and their definitions vary depending on who you ask.
| Rule | How it splits take-home pay | May suit |
|---|---|---|
| 50/30/20 | 50% needs, 30% wants, 20% savings | Most salaried workers starting out |
| 70/20/10 | 70% spending (needs and wants together), 20% savings, 10% debt repayment or giving | People who find it hard to separate needs from wants |
| 40/30/20/10 | 40% living expenses, 30% loan repayments, 20% savings, 10% insurance | Homeowners with loans who want insurance as its own line |
| Pay yourself first | A fixed amount (often 20% or more) saved first, the rest spent freely | People who dislike tracking categories |
| Your own split | Percentages you set around your goals | Those with specific targets, such as retiring early |
Which rule you pick matters less than staying with it. Give it a few months, and change the percentages when your life changes, not every time a bucket runs short.
The Limits of the 50/30/20 Rule
The 50/30/20 rule is a guide, not a target you’ll hit exactly every month. Its big strengths are that it’s easy to remember, needs no daily maths, and builds in money for enjoyment.
It does have limits, though:
- It treats all savings the same. It doesn’t tell you whether to build your emergency fund, invest, or buy protection first.
- It’s tricky with variable income. If you earn commission or freelance, budget on a typical low month rather than an average one.
- Your needs change with life stages. A new baby, a home purchase, or caring for ageing parents can push needs above 50% for years, especially with Singapore’s cost of living.
Budgeting Is Only One Part of Your Financial Plan
A budget only works while your income keeps coming in, which is why insurance planning matters. You can check whether you have enough life insurance in a few minutes.
Our 7-step guide to financial planning shows where budgeting fits in, and what to sort out before and after it.
Wrapping Up
If you’ve never budgeted before, the 50/30/20 rule is a good place to start. Your first month won’t match the percentages exactly, and that’s fine.
Work out your take-home pay, see where your money goes, and set up the transfers so your savings happen on payday. Knowing your monthly spending is already a good start. In our survey, fewer than half of adults did.
If you’d like help seeing how your budget, CPF, insurance, and investments fit together, our comprehensive financial planning session looks at your whole picture with a licensed consultant.
BEFORE YOU GO
Articles can tell you what generally makes sense. They can't see your policies, your CPF, or your plans.
FullCircle is our comprehensive financial planning session. A licensed consultant goes through what you have, shows you the gaps and overlaps, and tells you what to prioritise across protection, retirement, and estate planning.
It's complimentary, takes about 45 minutes, and if nothing needs changing, we'll say so.