
If you leave money in a savings account for 20 years, inflation can reduce how much it will buy.
That’s a real problem when the money has a job to do on a set date, like paying for your child’s university or funding your retirement.
An endowment plan is one way Singaporeans save for dates like these. This guide covers how they work, what to compare, and when one makes sense (and when it doesn’t).
Key Takeaways
- An endowment plan in Singapore is a life insurance policy with a savings component, not a bank deposit, and it pays out a lump sum or a series of payouts over a fixed term.
- Participating endowment plans add non-guaranteed bonuses on top of their guaranteed benefits, and these bonuses depend on how the insurer’s participating fund performs.
- Surrendering an endowment plan early can return less than the total premiums paid, and in the first few years the surrender value may be zero.
- Long-term endowment plans are usually paid with regular premiums and built around a goal many years away, while short-term plans are usually bought with a single premium and held for a few years.
- The guaranteed benefits of endowment plans are protected, subject to caps, under the Policy Owners’ Protection Scheme administered by SDIC.
SIDE NOTE
A policy bought years ago. Savings in three places. A will that's still on the to-do list.
None of it is wrong. It's just not a plan yet.
There's an order that turns the pieces into one system, and it doesn't require becoming a finance expert. Here's the order, in 7 steps, so you know what to sort out first.
What Is an Endowment Plan?
An endowment plan is a type of life insurance that combines saving with a small amount of protection.
You pay premiums for a set period. When the policy matures, it pays out, either as a lump sum or as a series of payouts.
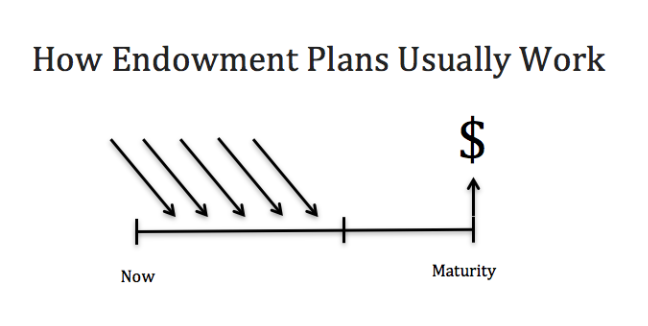
People often use endowments to save for a specific goal, such as a child’s education or retirement.
The government’s MoneySense programme calls endowments bundled products, because part of your premiums pays for insurance coverage while the rest is invested and carries risk.
This is where it differs from a fixed deposit. You may not get back everything you put in, especially if you stop early.
Besides the maturity payout, an endowment plan pays a benefit if you pass away during the policy term. Most also cover total and permanent disability, and some cover major illnesses, though the definitions vary from plan to plan.
How Do Endowment Plans Work?
When you buy an endowment plan, you choose three things: how much to pay, how long to pay for (the premium term), and when the policy matures (the policy term).
The two terms don’t have to match.
Many plans let you pay for a shorter period, then leave the policy to keep growing until it matures. This is often called a limited-pay structure.
Endowment plans in Singapore come in a few broad forms.
Participating endowment plans
A participating (par) endowment plan shares in the profits of the insurer’s participating fund.
Your premiums are pooled with those of other policyholders and invested in a mix of assets. According to MoneySense, these can include government and corporate bonds, shares, property, and cash.
Your share of the fund’s profits is paid to you as bonuses. These aren’t guaranteed until they’re declared.
Non-participating endowment plans
A non-participating (non-par) plan doesn’t share in the fund’s profits. Instead, its maturity value and cash values are guaranteed from the start.
You know exactly what you’ll get from day one. You just won’t get any bonuses on top.
Endowment plans that pay out along the way
Some plans, known as anticipated endowments, pay out part of the sum assured at set intervals during the policy term. The balance, plus any bonuses, is paid at maturity.
These can be participating or non-participating.
Retirement income plans are a closely related category. If a monthly income in retirement is your main goal, our comparison of retirement annuity plans is a better starting point.
Guaranteed vs Non-Guaranteed Returns
What you receive from a participating endowment plan comes in two parts.
The first is the guaranteed benefits written into your contract. The second is non-guaranteed bonuses, which depend on the participating fund’s investment returns, the claims it pays, and its expenses.
Not every endowment plan is capital guaranteed. On some plans, the guaranteed amount at maturity is less than the total premiums you pay, so you’d need the non-guaranteed bonuses to come through just to get your money back.
Reversionary bonuses
Reversionary bonuses are usually declared once a year and added to your policy.
Once declared, a reversionary bonus becomes part of your guaranteed benefits, and the insurer can’t reduce it or take it away.
There’s a catch, though. If you surrender the policy early, you may get back less than what you’ve put in.
Terminal bonuses
A terminal bonus is worked out only when the policy matures, when a claim is made, or when you surrender it.
If the fund is doing poorly at that moment, the terminal bonus could be low or even zero. So any part of a projected payout that relies on terminal bonuses is the least certain part.
Bonus smoothing
Insurers generally try to keep bonuses steady from year to year. They may hold back some returns in strong years so that bonuses can be kept up in weaker ones.
So a bad year in the stock market may not show up straight away in your bonus.
Smoothing only goes so far, though. If the fund performs poorly and the outlook stays weak, insurers can cut future non-guaranteed bonuses.
Once you own a par plan, you’ll receive an annual bonus update. It shows how the fund has performed, its outlook, and any bonus added to your policy that year.
QUICK CHECK
Can you answer these three questions?
1) If something happened to you tomorrow, how much would your family receive?
2) At 65, what monthly income will your savings and investments pay you?
3) If you never get round to a will, who inherits what, and in what proportion?
Most people manage one at best. Not because they're careless, but because nobody has shown them which order to tackle things in.
That order exists. Work through your finances in this sequence, from income and protection through to investments and estate planning.
Short-Term vs Long-Term Endowment Plans
Endowment plans in Singapore broadly fall into two groups.
| Feature | Short-term endowment plans | Long-term endowment plans |
|---|---|---|
| Typical duration | A few years | 10 years or more |
| How you pay | Usually a single lump sum | Usually regular premiums (monthly or yearly) |
| Returns | Often mostly or fully guaranteed | Guaranteed benefits plus non-guaranteed bonuses (for par plans) |
| Main use | Parking spare cash for a short period | Saving steadily towards a goal years away |
Short-term plans are often available only for a limited period. Because they’re used to park spare cash, it makes sense to compare them with fixed deposits, Singapore Savings Bonds, and Treasury bills.
Long-term plans are built around a goal with a fixed date, such as a child starting university or your planned retirement age.
Why long-term plans are worth a closer look
Endowment plans tend to work best when they’re used as intended, for disciplined savings towards a goal that’s many years away.
A few reasons stand out.
- Declared bonuses add up. For par plans that pay reversionary bonuses, each year’s declared bonus becomes guaranteed. Over a longer term, more of your benefits move from non-guaranteed to guaranteed.
- Early costs have time to even out. Distribution costs are largely taken from premiums in the early years, which is why early surrender values are low. A longer holding period gives your policy time to recover from them.
- Regular saving builds the habit. Premiums can be deducted automatically, so saving happens before spending.
- Short-term money has simpler options. For cash you’ll need within a few years, Singapore Savings Bonds and Treasury bills are backed by the Singapore Government and don’t tie you to an insurance contract.
The flip side is commitment. A long-term plan only works if you can keep paying the premiums comfortably for the whole premium term, so be honest with yourself about that before you sign up.
Pros and Cons of Endowment Plans
Pros
- Disciplined saving. Fixed premiums turn saving into a routine rather than something you do with whatever is left over.
- Part of the payout is guaranteed. The guaranteed benefits in your contract give you more certainty than investing directly in shares. Depending on the plan, though, the guaranteed amount may be less than the total premiums you pay.
- Steadier growth. Bonus smoothing means participating plans don’t rise and fall with the markets the way shares do.
- Some protection included. You get a death benefit, and usually cover for total and permanent disability as well.
- Simpler applications for some plans. Savings-focused plans with minimal coverage may ask few or no health questions, which can help if you have pre-existing conditions. This varies by plan, and adding riders may require you to answer health questions.
Cons
- Bonuses aren’t guaranteed. The final payout from a par plan may be lower than what was illustrated when you bought it.
- Leaving early can cost you. Surrender values in the early years can be well below the premiums paid.
- Your money is tied up. You can take a policy loan against the cash value, but the interest charges can be steep, and any unpaid amount is deducted from your cash value or claim payout.
- Opportunity cost. A par fund invests across bonds, shares, and other assets, and smooths its returns. If you have a long time horizon and are comfortable with market swings, investing directly in shares or stock market index funds may grow your money more over time, though with bigger ups and downs and no guarantees.
- You pay for insurance you may not need. If protection is what you’re after, term life insurance is usually the more efficient tool.
What Happens If You Surrender an Endowment Plan Early?
If you surrender (cancel) an endowment plan before it matures, you’ll receive its surrender value. This may be less than the premiums you’ve paid, or even zero.
The risk is highest in the early years. A policy may have no cash value in its first three years, because most of the premiums go towards distribution costs.
For par plans, the surrender value includes only part of the bonuses declared so far, and it could be lower than what was illustrated when you bought the policy. Charges and anything you owe the insurer, such as an outstanding policy loan, are deducted too.
The one low-cost exit is right at the start. New policies come with a 14-day free-look period, which starts from the date you receive the policy document. If you cancel within this period, the insurer refunds your premiums.
How to Compare Endowment Plans
There’s no single best endowment plan for everyone. The right one depends on your goal, your timeline, and how much you can set aside.
Most of what you need is in the policy illustration and product summary. Here’s what to check:
- Match the maturity date to your goal. The payout should arrive when you need the money, not years before or after.
- Test the premium term against your budget. Ask yourself whether you could keep paying if your income dipped for a while. On some plans, paying yearly costs slightly less overall than paying monthly, so compare the premium for each mode.
- Compare the guaranteed maturity value with your total premiums. This tells you whether your capital is guaranteed at maturity, and by how much.
- Plan around the lower illustrated rate. Policy illustrations for par plans show projected benefits at two illustrated investment rates of return. Under the Life Insurance Association’s guidelines, neither rate is an upper or lower limit on how the fund will actually perform. Using the lower one keeps your expectations grounded.
- Find the breakeven year. In the surrender value table, look for the year when the total surrender value first exceeds the total premiums you’ve paid. Check it at the lower illustrated rate and on a guaranteed-only basis. The earlier it arrives, the less an unexpected exit would cost you.
- Read the product summary. For par plans, it describes the participating fund’s investment strategy and broad mix of assets, so you can see what’s driving the bonuses.
- Ask about flexibility. Find out whether the plan allows partial withdrawals, what happens if you miss a premium, and which riders are available, such as one that waives future premiums if you become seriously ill.
If you’re buying through an adviser, ask them to walk you through each of these figures before you sign.
How Safe Is Your Money in an Endowment Plan?
The guaranteed benefits of life insurance policies, including endowment plans, are protected under the Policy Owners’ Protection (PPF) Scheme, subject to caps.
The scheme is run by the Singapore Deposit Insurance Corporation (SDIC). Coverage is automatic, with no form to fill in and no premium to pay, as the levies are paid by member insurers.
For non-par plans, all benefits count as guaranteed. For par plans, it covers the guaranteed benefits plus any bonuses already declared and vested, but not future non-guaranteed bonuses.
For more on the caps and how the scheme compares with deposit insurance, see our guide to SDIC.
Is an Endowment Plan Right for You?
An endowment plan may suit you if:
- You have a goal with a fixed date that’s at least 10 years away
- You want part of your savings guaranteed, rather than fully exposed to the ups and downs of the stock market
- You already have an emergency fund and your insurance protection in place
- You like having your saving done automatically
It may not suit you if:
- There’s a real chance you’ll need the money before the plan matures
- Protection is your main goal
- You’re comfortable with market swings and would rather invest directly for potentially higher long-term growth
Take Daniel, 35, whose daughter has just turned three. A long-term endowment plan that matures when she turns 18 means the money is ready before she starts university. He picks a premium he could keep paying even in a lean year, which matters more to him than a slightly higher projected return.
The order matters too. Build your emergency fund and get adequately protected first, then decide how much of your long-term savings to put into an endowment plan.
If you’re not sure how an endowment would fit alongside your CPF, existing policies, and investments, our comprehensive financial planning session looks at the whole picture first.
Final Thoughts
An endowment plan is a slow, steady way to build up a sum for a goal you can see coming, with part of the payout guaranteed.
The main risks are taking on premiums you can’t keep up with, or needing the money back before the plan has had time to grow.
So take your time with the policy illustration. Base your expectations on the guaranteed and lower illustrated figures, and pick a premium you’d still be comfortable paying in a tight year.
Once you’ve bought a plan, note its key dates and values in your insurance policy summary so you and your family know what you hold.
And if you’d like help seeing how it fits into your wider plans, see how FullCircle works.
BEFORE YOU GO
Articles can tell you what generally makes sense. They can't see your policies, your CPF, or your plans.
FullCircle is our comprehensive financial planning session. A licensed consultant goes through what you have, shows you the gaps and overlaps, and tells you what to prioritise across protection, retirement, and estate planning.
It's complimentary, takes about 45 minutes, and if nothing needs changing, we'll say so.